 By
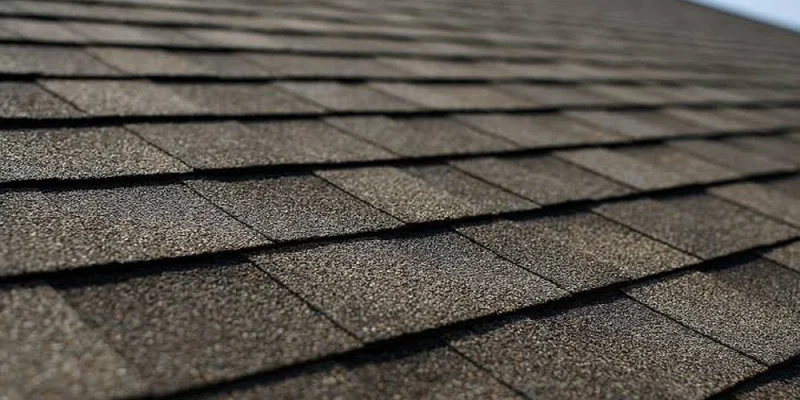
Anyone who has lived through an Oklahoma spring knows the sequence: the sky turns green, the sirens sound, and a few minutes later golf ball sized ice is hammering the roof. The storm itself is over quickly. The harder part is the weeks that follow, when you are expected to understand adjuster reports, deductibles and depreciation while a stranger knocks on your door offering a “free inspection.” A reliable Oklahoma City roofing contractor can help you read the damage and the paperwork, but you will make better decisions if you already speak the language. This glossary covers the terms that matter most when a storm meets your roof.
Terms About Your Policy
Wind and hail deductible. Many Oklahoma policies use a separate deductible for wind and hail, often a percentage of your dwelling coverage rather than a flat dollar amount. One percent of a $300,000 dwelling limit means $3,000 out of pocket before coverage begins. Find this figure on your declarations page before a storm, not after.
Actual cash value (ACV). This pays the cost of the roof minus depreciation for its age and condition. A fifteen year old roof may be valued at a fraction of what a new one costs.
Replacement cost value (RCV). This pays closer to the full cost of a new roof. Some policies pay ACV first and release the remaining amount, called recoverable depreciation, only after the work is finished and documented.
Roof surfacing payment schedule. Some insurers apply an age-based schedule that reduces roof payouts as the roof gets older, no matter how well it was maintained. Ask your agent whether your policy includes one.
Cosmetic damage exclusion. Certain policies, particularly for metal roofs, refuse to pay for dents that do not affect how the roof functions. Know whether yours has this clause.
Terms About the Damage
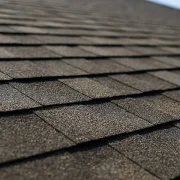
Bruising. Hail can crush the asphalt mat beneath the granules without puncturing the shingle. The spot feels soft or spongy when pressed. It looks minor but shortens the roof’s life significantly.
Granule loss. Hail knocks protective granules off shingles, exposing the asphalt underneath. Check your gutters and downspout exits for piles of grit.
Collateral damage. Dented gutters, damaged vents, pitted AC condenser fins and dinged window screens are clues. They help confirm hail size and direction, and they support a claim even when roof damage is hard to see from the ground.
Test square. Adjusters often count hail hits within a ten foot by ten foot area on each slope. The count helps decide between repair and replacement, so ask which slopes were measured and what the totals were.
Wind creasing. A horizontal line across a shingle where it folded back in high wind. Lifted or missing tabs are often covered under wind provisions.
Terms About the Process
Claim deadline. Policies set time limits for reporting storm damage, sometimes as short as one year from the date of loss. Report promptly, even if you are unsure about the damage.
Adjuster. The insurer’s representative who inspects the damage and estimates the cost. You are allowed to be present and to have a contractor of your choice on the roof at the same time.
Scope of loss. The adjuster’s written list of damage and repair costs. Compare it to your contractor’s estimate line by line. Missing items such as drip edge, ventilation, underlayment or code-required upgrades are common reasons for supplements.
Supplement. A follow-up request for items missed in the first estimate or for hidden damage found during tear off. Legitimate supplements come with photographs and documentation.
Reinspection. If you disagree with the findings, you can ask the insurer to look again, ideally with your contractor’s photos and measurements in hand.
Terms About Contractors
Storm chaser. An out-of-area crew that appears within days of a major storm, collects deposits and disappears before the work is finished or the warranty matters. Be careful with anyone who pressures you to sign immediately.
Assignment of benefits. A document that transfers your claim rights to a contractor. Read it very carefully, because it can limit your control over the claim.
Deductible waiver. An offer to cover or “make disappear” your deductible. In Oklahoma, this practice is restricted by law and can put your claim at risk, so treat it as a warning sign and confirm current rules with the state insurance department.
Your First Seven Days After a Storm
- Stay safe. Do not climb onto a wet or damaged roof.
- Photograph everything from the ground. Capture roof edges, gutters, siding, vehicles, patio furniture and any hail stones with a coin for scale.
- Prevent further damage. Tarp exposed areas and keep receipts, since reasonable temporary repairs are normally part of your duties under the policy.
- Read your policy. Find the deductible, the claim deadline and any roof-specific clauses.
- File the claim and record the claim number. Keep a log of every call, name and date.
- Get an independent inspection. Choose a licensed, insured local contractor with verifiable references, and ask for a written report with photographs.
- Meet the adjuster. Be present, share your documentation and ask questions about anything that is unclear.
Rebuilding Smarter
If your roof needs replacement, think about durability as well as price. Impact-resistant shingles, stronger underlayment and upgraded fastening can reduce future losses and may qualify for insurance discounts. The Insurance Institute for Business and Home Safety runs the roof standard, a construction approach designed to help roofs withstand severe wind and storms, and Oklahoma has supported it through state programs. It is worth reading about before you choose materials.
Questions to Ask Before Signing Anything
- Is the contractor licensed, insured and locally established, with a physical address and references?
- Does the written estimate match the insurer’s scope, and are differences explained?
- Who handles permits, supplements and cleanup?
- What are the workmanship and manufacturer warranties, and who stands behind them?
- When will payments be due, and how do they relate to insurance payouts?
Final Thoughts
A hailstorm is stressful enough without a vocabulary test. Learn your deductible, document the damage, understand how the adjuster measures it and be wary of anyone who rushes you. When you know the terms, you stay in control of the claim, and you can hold the right professionals accountable for a repair that lasts through the next storm season.
Comments